
TL;DR
- Zillow Home Loans announced a second loan of up to 3.5% of the lower of purchase price or appraised value, with 0% interest and no monthly payment.
- Forgiveness requires 5 years of on-time primary-mortgage payments and owner occupancy. The second loan is due in full if the buyer moves out, sells, or refinances before year 5.
- Before choosing Zillow Home Loans or making an offer, confirm availability for you and the Austin-area property in writing, then compare the full FHA costs and second-loan terms with other financing options.
If you can afford a home’s ongoing payment but need help with the down payment, this program may reduce the cash you must supply upfront. The trade-off is a repayment obligation tied to how long you occupy the home and keep the primary mortgage. These are the terms in Zillow Home Loans’ October 28, 2026 announcement, checked in the supplied evidence on November 2. Confirm current terms and eligibility in writing before relying on them.
A $400,000 purchase shows what you gain—and still owe
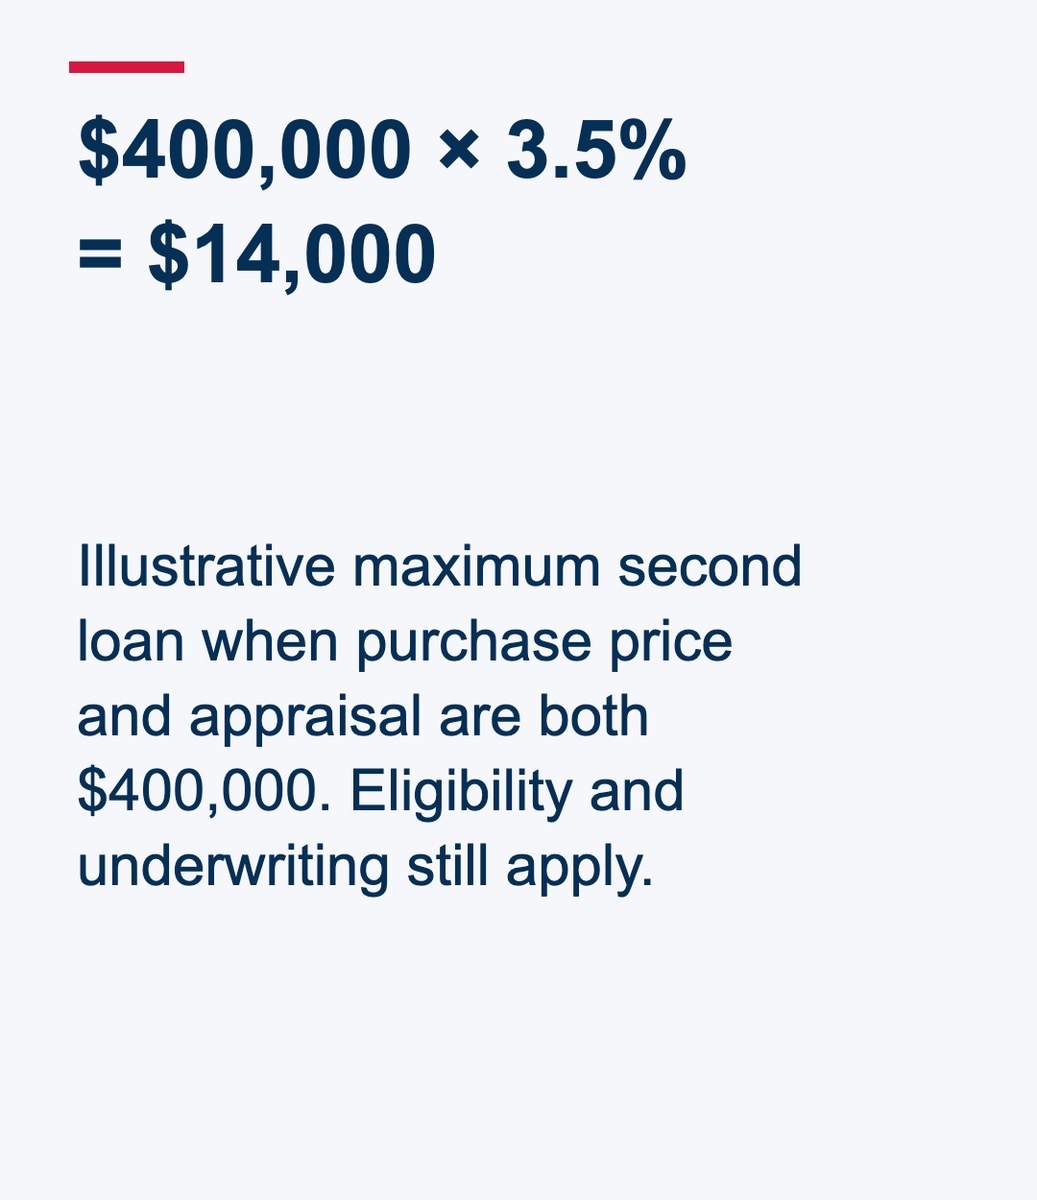
Suppose you buy an Austin-area home for $400,000 and it appraises for $400,000. At the announced maximum, $400,000 × 3.5% produces a $14,000 second loan, subject to eligibility and underwriting. That is money available toward the down payment, not an unconditional gift at closing.
If this hypothetical buyer sells in year 3, Zillow says the $14,000 second loan is due in full. The same repayment trigger applies if the buyer refinances or moves out before year 5. Remaining in the home alone is not enough for forgiveness: the announcement requires 5 years of on-time primary-mortgage payments and owner occupancy. Source: Zillow’s announced repayment conditions.
The benefit is keeping cash that otherwise would go toward the down payment. The cost is having to account for that debt if plans change. A buyer expecting a short stay should compare a financing path without this repayment condition, even if it requires more cash upfront. A buyer expecting to stay may find the assistance useful if the full payment is affordable and competing quotes support the choice.
This example does not estimate closing costs, cash to close, FHA mortgage insurance, the interest rate, or savings versus another loan. If the appraisal is below the purchase price, the announced assistance cap uses that lower value; do not budget from the purchase price alone.
Who qualifies, and what “no monthly payment” means
A second loan is a separate debt alongside the main mortgage. Here, “no monthly payment” describes the assistance loan. It does not remove the monthly payment on the primary mortgage.
Zillow’s announced requirements include a minimum 640 credit score, an FHA loan with Zillow Home Loans, a primary-residence purchase, and qualification for the full monthly mortgage payment under standard underwriting. FHA is the Federal Housing Administration; its mortgage insurance applies to this loan. A qualifying score alone does not establish approval.
This is a lender-specific option, not an Austin public grant. Texas is not among the announcement’s named exclusions, but that does not establish availability for every Austin-area buyer or property. Obtain written confirmation from Zillow for both before making an offer or selecting this financing.
Compare the mortgage and assistance together
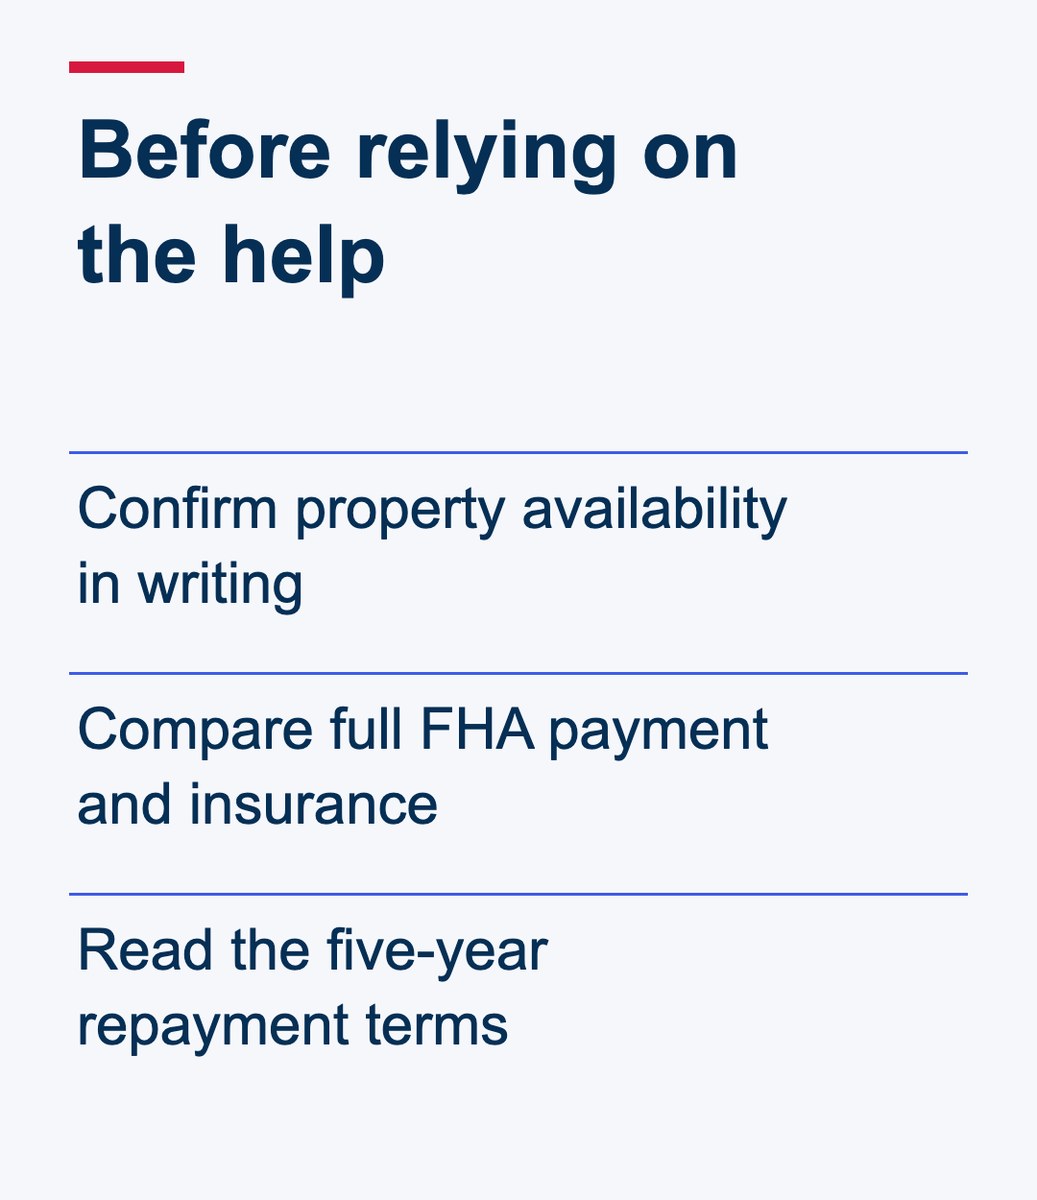
Ask Zillow for a written Loan Estimate—the document outlining the proposed mortgage’s terms and estimated costs—and the written second-loan terms. Obtain a competing financing quote for the same purchase and compare these items:
- Primary rate and full payment: Compare the mortgage payment, FHA mortgage-insurance costs, and property-specific taxes and homeowners insurance. Assistance with the down payment does not establish that the ongoing housing cost fits your budget.
- Cash to close and reserves: Identify the cash still needed to complete the purchase, any lender-required reserves, and what you will have left for repairs and emergencies. Do not treat the assistance amount as the entire cash-to-close calculation.
- Cost of changing plans: Have Zillow identify the full repayment obligation if you sell, refinance, or cease owner occupancy before year 5. For another assistance offer, compare its own repayment and forgiveness terms rather than assuming they match.
- Eligibility and availability: Confirm the 640-score requirement, qualification for the full payment under standard underwriting, primary-residence use, and availability for your specific property. Resolve those items before treating the help as committed funding.
Depending on your eligibility, the comparison could include another FHA loan, conventional or VA financing, or state, local, employer, nonprofit, or other lender assistance. Zillow’s announcement does not establish that its option is cheaper than those alternatives. Use actual written offers to decide.
Match the five-year conditions to your Austin-area home search
Apply the comparison to the home you intend to buy, whether that is in Austin, Round Rock, or another nearby community. Use that property’s tax and insurance estimates, and consider whether its location and size suit your expected needs for the full occupancy period. A city name does not establish program eligibility or the monthly cost.
If your plan is to move out and rent the home before year 5, the announced move-out trigger still matters even if you keep ownership. If your plan depends on refinancing soon, include repayment of the second loan when evaluating that future transaction. A lower future rate is uncertain, and any future refinance would still require qualification.
Frequently asked questions
Must I be a first-time buyer or fall below an income limit?
The announcement states no first-time-buyer requirement and no announced income cap. That does not waive the other requirements or guarantee approval. Ask Zillow to confirm current eligibility for your application in writing. Source: Zillow’s program announcement.
What happens if a primary-mortgage payment is late?
The stated forgiveness condition is 5 years of on-time primary-mortgage payments and owner occupancy. The supplied announcement does not resolve how a late payment affects forgiveness or whether any remedy is available. Before accepting the loan, obtain the written definition of an on-time payment and the consequences of missing that condition; do not assume forgiveness will still occur.
Does forgiveness after year 5 eliminate the main mortgage?
No. The announced forgiveness applies to the assistance second loan after its conditions are met. The primary mortgage remains a separate obligation. Ask how Zillow documents fulfillment of the conditions and confirms forgiveness before treating the second-loan balance as cleared.
Sources
- Zillow Home Loans will now help eligible buyers cover their FHA down payment — October 28, 2026; verified evidence checked November 2, 2026. Lender announcement of its own program; current terms, availability, underwriting, and closing documents require written confirmation.
Recommended reading
- Austin Down-Payment Assistance: Compare Saving Time and Housing Costs
- Austin Down-Payment Assistance: When a Bigger Grant Can Mean a Bigger Decision Later
Before you make an offer, contact Vladimir Baibus · ATXCasa, LPT Realty for help matching your Austin-area home search to your housing budget and expected stay, and organizing the property-specific questions your lender needs to resolve.