
TL;DR
- Zillow and Thumbtack’s $16,566 annual estimate describes a modeled typical U.S. homeowner. Their supplied metro table has no Austin result.
- Before an Austin-area offer, compare each address’s insurance quote, applicable tax estimate and verified exemptions, known near-term maintenance, and HOA dues if applicable.
- Check which costs the lender’s payment already includes. Count each expense once, and separate recurring costs from work that needs cash soon.
Should you add about $1,380 to a mortgage payment when deciding what Austin home to buy? No—not automatically. That figure comes from Zillow and Thumbtack’s national model, not the home you are considering. Using it as your own allowance can distort both your monthly budget and the cash you need for upkeep.
The useful takeaway is to check the categories behind the headline. Before choosing between homes, replace the benchmark with address-specific information and compare it alongside the lender’s loan estimate. A home with a manageable loan payment can still require more near-term cash than you want to commit.
What Zillow’s $16,566 estimate actually measures
The October 22, 2026 Zillow and Thumbtack release reports $16,566 annually, or about $1,380 monthly, for insurance, maintenance and property taxes for the typical U.S. homeowner. It reports annual components of $11,171 for maintenance, $2,266 for homeowners insurance and $3,129 for property taxes.
These are modeled costs. Zillow estimated property taxes and homeowners insurance for a typical homeowner in each analyzed metro. Thumbtack supplied maintenance estimates using a weighted index of recommended projects, calculated quarterly with a moving average. That maintenance figure is not a repair forecast for an individual house.
Austin does not appear in the supplied metro table. The release therefore provides no Austin average to plug into an offer budget. Its value here is as a reminder to investigate costs that the purchase price alone cannot explain.
Compare two Austin homes with the same loan payment
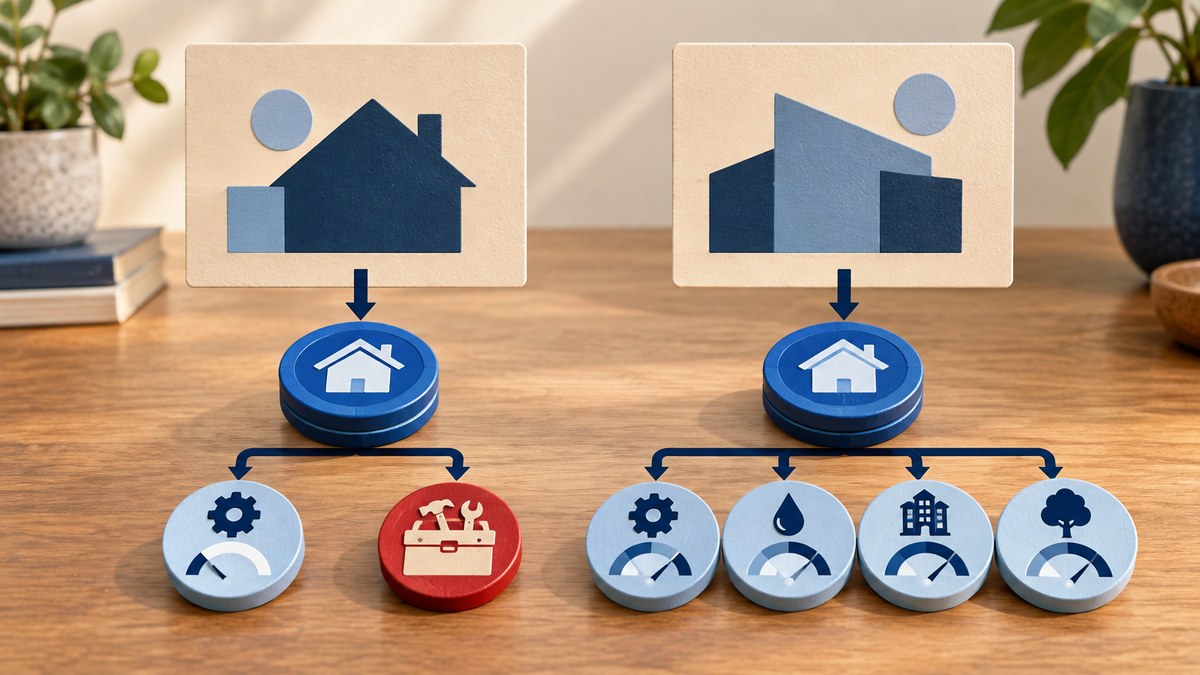
Consider a hypothetical buyer comparing Home A and Home B with the same lender-provided principal-and-interest payment—the amount going toward the borrowed money and interest—and the same intended down payment. Neither address has supplied dollar estimates here; this example explains the decision without inventing Austin prices.
Suppose the completed property checks show that Home A has lower recurring costs but a known repair that needs attention soon. Home B has higher recurring costs, including HOA dues, but no comparable near-term work identified through due diligence. That finding does not guarantee Home B will be repair-free.
If Home A’s repair would use cash the buyer needs to retain after closing, its lower monthly cost does not resolve the immediate problem. Home B may be the more manageable choice if its documented recurring budget fits. If the buyer can fund Home A’s work while retaining enough cash for other needs, Home A remains a reasonable option. If neither fits, keep searching or lower the purchase budget.
The comparison needs both a recurring budget and a list of near-term cash needs. Spreading an urgent repair across a monthly planning allowance does not make the money available when the repair is due.
Build the comparison from each address
Use the same fields for each home on your Home search shortlist. Record where each estimate came from and what still needs confirmation.
- Insurance: Obtain a property-specific homeowners-insurance quote before making an offer. The source expressly recommends this because the cost to insure a specific home can change affordability. Use the quoted terms when comparing homes, rather than substituting the national insurance component.
- Property taxes: Record the applicable property-tax estimate after confirming applicable exemptions. Keep any unverified exemption status visible; do not make the home fit your budget by assuming a tax benefit has been confirmed.
- Maintenance: List known near-term maintenance identified through due diligence, with its expected timing and any available cost estimate. Keep that work separate from an allowance for ongoing upkeep so you can see what needs funding soon.
- HOA obligations: Add homeowners association dues if applicable and identify any other documented HOA obligations relevant to the purchase. A blank field is not confirmation that no obligation exists.
- Loan estimate: Compare these entries with the lender’s loan estimate. If the payment shown already includes taxes or insurance, mark them as included rather than adding them again. If they are excluded, account for them separately.
For the recurring comparison, put expenses on the same time basis and count each once. Keep the cash needed for the down payment, closing and known near-term work visible separately. Also leave room in your household budget for utilities and other expenses outside the national bundle; its headline is not a complete spending plan.
This takes more work than adding a national allowance, and some estimates will remain provisional before an offer. The benefit is that you can identify what would actually change the decision: an insurance quote, a confirmed tax assumption, an HOA obligation or a repair you cannot comfortably fund.
Frequently asked questions
What if one home has a missing quote or an unresolved repair estimate?
Treat that comparison as unfinished. Request the missing property-specific information and identify whether the unresolved item could change your choice. If it could, defer the choice until you can assess it; the national benchmark does not resolve the uncertainty. Review any proposed contract timing with your agent so your plan to obtain information fits the actual decision deadlines.
What should I revisit after closing?
Use the purchase worksheet as a starting record. Update it when you receive new insurance terms, tax information, HOA notices or maintenance estimates. After completing a planned repair, remove that completed item from the upcoming-work list and reassess what comes next. Keeping the record current helps you distinguish a completed expense from an ongoing funding need.
Sources
- Zillow Group and Thumbtack: “Hidden costs of homeownership top $16.5K/year, up nearly 32% in 5 years” — October 22, 2026. National modeled costs, methodology and insurance-quote recommendation; no Austin result in the supplied metro table.
Recommended reading
- Buying an Older Austin Home? Get the Insurance Quote Before the Option Period Ends
- Buying an Austin HOA Home? Get the Resale Certificate Before Your Review Window Closes
Choosing between Austin-area homes? Contact Vladimir Baibus · ATXCasa, LPT Realty for help organizing the address-by-address cost comparison and identifying which missing information could change your offer budget.