
TL;DR
- USDA’s Guaranteed path offers no-money-down purchase or build financing in eligible rural areas for moderate-household-income applicants.
- Check the exact address and household in USDA’s current eligibility tools. Results indicate potential eligibility, not approval.
- If the address appears eligible and the household appears within the applicable income guidance, choose a participating lender for a full application assessment.
- No down payment does not establish that closing costs, lender fees or other transaction expenses are zero.
If you are looking beyond Austin and a no-down-payment loan could make buying more manageable, USDA Guaranteed financing may be worth exploring. The useful first question is whether the specific home and your household fit the program’s preliminary checks. A rural setting or community name alone is not enough to establish that fit.
USDA Rural Development’s housing guidance, checked October 28, 2026, describes the Guaranteed path as “Purchase or build with no money down in eligible rural areas,” for moderate household income, with 30-year fixed rates. It directs applicants to an active lender. That creates a potential benefit—buying without a down payment—but the address, household and full application still need assessment.
Two homes can lead to different financing decisions
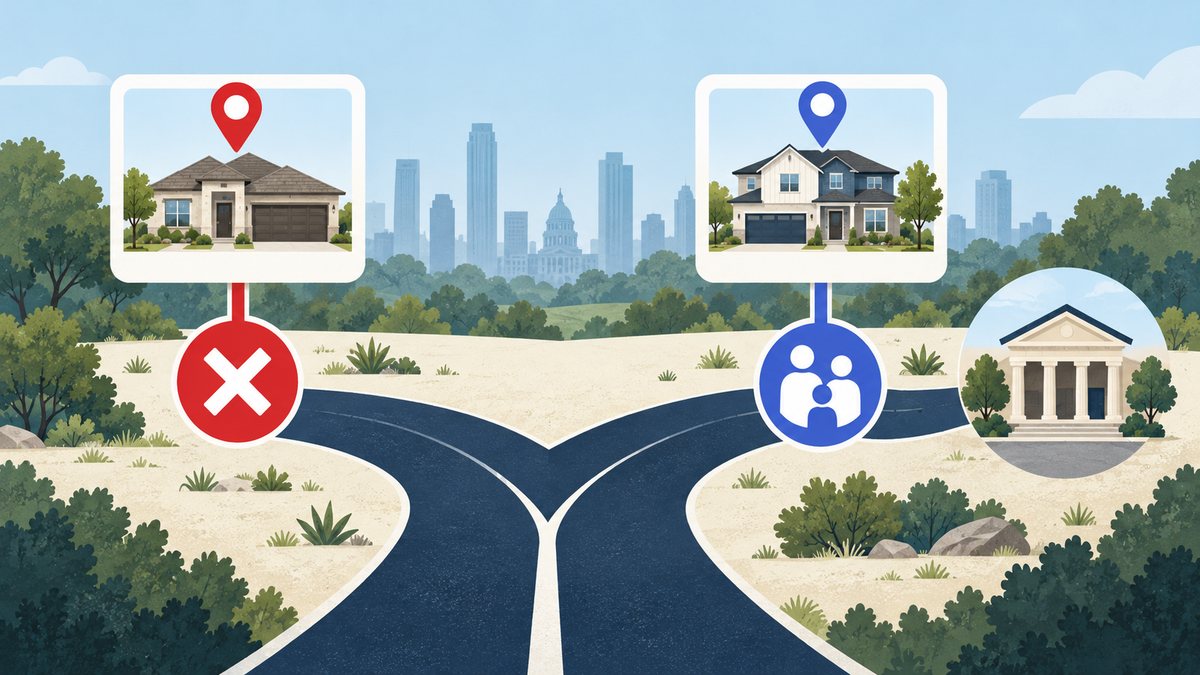
Consider a hypothetical household comparing Home A and Home B in rural Central Texas before making an offer. No actual property or income amount is assumed here.
The household enters Home A’s exact address in USDA’s rural/Guaranteed eligibility tools and checks its household in the income tool. Suppose the address is not eligible. The household should not rely on a USDA Guaranteed no-down-payment conversation for that property. Keeping Home A on the shortlist would mean exploring another financing option it can qualify for and afford.
The household repeats both checks for Home B. Suppose Home B appears eligible and the household appears within the applicable income guidance. The next step is to choose a USDA participating/active lender for a full application assessment. Home B is a candidate for further review; the tool results do not approve the home, household or loan.
This example applies USDA’s potential-eligibility guidance to a Central Texas search. It does not verify eligibility for any local address. The decision changes because of the specific address and household results, not because one home looks more rural.
Guaranteed and Direct loans use different application paths
USDA’s program overview distinguishes the moderate-household-income Guaranteed path, which says “Apply through an active lender,” from the low- or very-low-income Direct path, which routes applicants directly to Rural Development. Both are described as no-money-down rural purchase/build paths, so that phrase alone does not tell you which program someone is discussing. Source: USDA’s program comparison.
When discussing financing, name the program: “I want to explore the USDA Guaranteed Loan Program.” If the low- or very-low-income description is closer to your situation, review the Direct path separately. Neither description by itself establishes your household’s eligibility.
Check the property before narrowing your search
For an Austin-area buyer considering rural Central Texas, use exact addresses as the starting point. An entire town should not enter or leave your search solely on an assumption about USDA eligibility. This is an application of national guidance, not a finding that any particular Central Texas community qualifies.
- Check each candidate address. From USDA’s housing programs page, follow the Eligibility Site links for Guaranteed Program Eligibility and rural-area mapping. Use the current tools for the exact property.
- Check the household with the income tool. Follow the applicable income guidance for that household and location; do not substitute a general impression that your income is “moderate.”
- Take potentially eligible results to a participating lender. If the address appears eligible and the household appears within the applicable income guidance, request a full application assessment. Ask what remains unresolved before relying on this financing for an offer.
As you use the Home search, keep each property’s eligibility result with its listing. Repeat the address and household checks for another candidate rather than carrying a favorable result from one property to the next.
Decide whether the whole purchase fits your budget
The no-down-payment feature can reduce the upfront cash needed for a down payment. It does not answer how much cash the complete transaction requires. USDA’s overview does not state that every closing cost, lender fee or other transaction expense is zero. Source: USDA’s program description.
Ask the participating lender for an itemized estimate of cash needed to close and the ongoing monthly payment, including what the estimate includes or excludes. Then compare those amounts with your available cash and monthly budget. A favorable eligibility screen is useful only if the full application and actual costs also work.
Pursue the Guaranteed path when both preliminary checks are favorable and the lender’s assessment supports a workable purchase. If the address does not fit, consider another property or another financing option. If the costs do not fit, adjusting the price range or waiting may be more useful than continuing to shop around a no-down-payment headline.
Frequently asked questions
Can I explore USDA Guaranteed financing for building a home?
USDA’s overview includes both purchasing and building in eligible rural areas for the moderate-household-income path. That supports exploring the option, but it does not establish that a particular site, construction plan or borrower qualifies. Check the exact address and household using the current tools, then have a participating lender assess the proposed application. Source: USDA Rural Development.
Who can clarify a confusing eligibility-tool result?
USDA encourages readers to contact it with questions or requests for clarification about potential eligibility. Use the contact options on its housing programs page for that clarification; the Guaranteed financing application itself goes through a participating lender. USDA housing programs and eligibility guidance.
Sources
- USDA Rural Development: Single Family Housing Programs — national program descriptions and links to eligibility tools; checked October 28, 2026. This source does not establish qualification for a particular Central Texas property or household.
Recommended reading
- Could a USDA Direct Loan Fit Your Central Texas Home Search? Check the Rural Address and Household Rules First
- Mortgage Quote Higher Than the Headlines? Compare the Loan, Not Just the Rate
Want help shaping a Central Texas home search around the properties you are considering and your financing questions? Contact Vladimir Baibus · ATXCasa, LPT Realty to organize a property shortlist and the address-specific questions to take to a participating lender.