
TL;DR
- The CFPB and DOJ withdrawal of their earlier statement does not establish automatic mortgage approval or denial for a noncitizen applicant.
- The agencies say lenders may consider immigration or citizenship information in specified circumstances. That is not an individual eligibility decision.
- Before choosing a lender, provide accurate borrower information and request its loan program, required documentation, and remaining underwriting conditions in writing.
- Comparing those answers takes time, but helps you identify unresolved financing questions before planning a purchase around an initial conversation.
If you are planning to buy an Austin-area home without U.S. citizenship, a lender’s preliminary “you may qualify” can leave an important question unanswered: what must it verify before you can rely on that answer? A federal agency announcement cannot fill that gap. The practical next step is to get the lender’s requirements for your circumstances and intended loan program before selecting a lender or making purchase plans that depend on financing.
What the federal withdrawal actually says
The Consumer Financial Protection Bureau (CFPB) and Department of Justice (DOJ) withdrew their joint statement about creditors’ consideration of immigration status under the Equal Credit Opportunity Act (ECOA). The CFPB announcement, last modified January 12, 2026, identifies the earlier statement as published October 12, 2023. This is dated background, not a new Austin lending announcement.
The agencies say ECOA and Regulation B, the regulation implementing that law, permit creditors to consider pertinent elements of creditworthiness and information necessary to protect creditor rights and remedies, including a borrower’s immigration or citizenship status. In plain language, the statement concerns information relevant to repayment and the lender’s ability to enforce its rights. Keep that qualification attached to the claim: it does not say that citizenship alone settles every application.
The announcement does not establish automatic mortgage approval or denial for any noncitizen applicant. It is not a loan-program eligibility guide or a universal document checklist. Underwriting—the lender’s review of whether a proposed loan meets its requirements—still needs to address the specific borrower and program.
A useful comparison: the same buyer, different answers
Consider this hypothetical example. A buyer is comparing two lenders for the same intended Austin-area purchase and gives each the same accurate borrower information.
Lender A identifies a loan program, supplies a written list of required lawful-residence, immigration or citizenship documents, and explains which underwriting conditions remain. Lender B offers an encouraging preliminary answer but has not yet identified the program or documents it will require.
Lender A’s response gives the buyer a concrete next step: check whether the requested documents are available and clarify any condition the buyer cannot yet meet. Lender B’s response calls for a follow-up before the buyer treats it as a workable financing plan. Neither response, by itself, is final loan approval.
The provisional choice is to advance the application whose requirements you understand and can address. That recommendation changes if its written conditions reveal something unresolved, or if the other lender supplies a suitable program and clear requirements. A shorter checklist or a more enthusiastic conversation is not enough to establish which loan is the better fit.
Requesting comparable answers takes effort and may slow your lender selection. The benefit is discovering an unresolved eligibility question while you can still adjust your purchase plans, instead of discovering it after building those plans around a preliminary answer.
What to request before selecting a lender
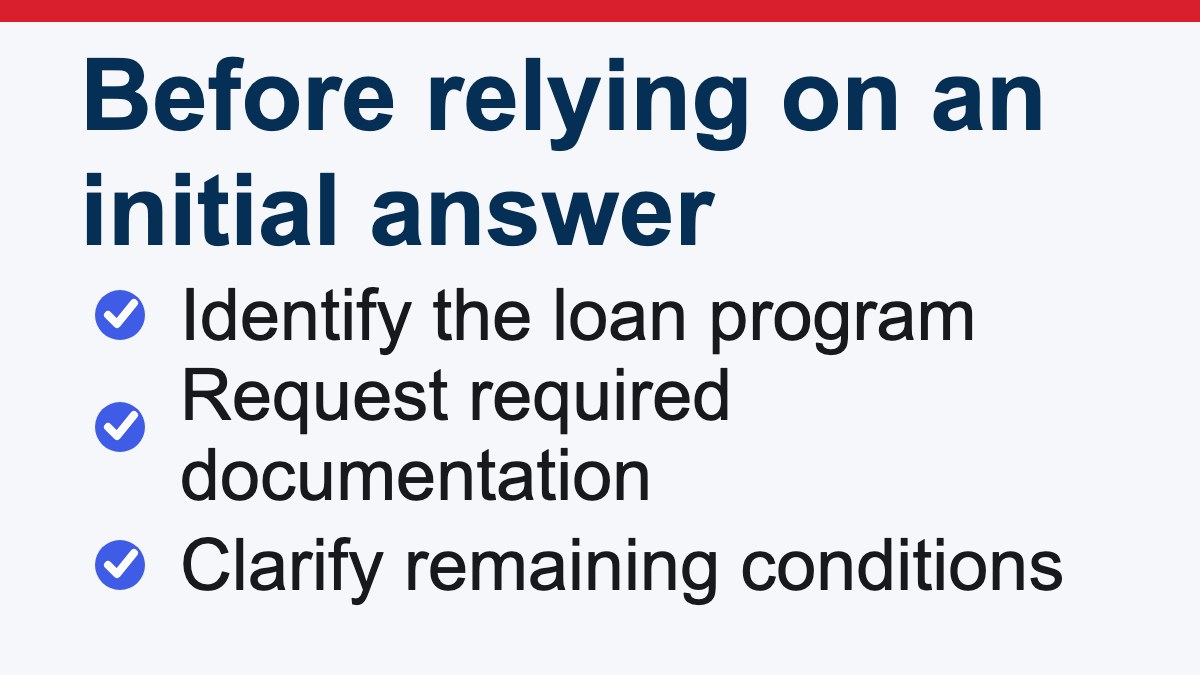
For each prospective lender, describe the same intended purchase and your accurate circumstances. Ask for these answers in writing:
- Which specific loan program are you evaluating for me? This identifies the program behind the preliminary answer.
- What lawful-residence, immigration or citizenship documentation do you require for my circumstances? This lets you identify documents you can provide and requirements that need clarification.
- Which remaining underwriting conditions must be met before I rely on this initial eligibility conversation? This separates an encouraging starting point from the review still ahead.
After you submit the requested documents, ask what the lender has reviewed and what remains outstanding. A document list is a starting point, not evidence that the documents have been accepted. If your circumstances or proposed loan program change, ask the lender to confirm which requirements now apply.
If a required document or condition remains unresolved, pause purchase commitments that depend on that financing answer. You can seek clarification or compare another lender using the same accurate information; neither step guarantees a different outcome.
How to apply this to an Austin home search
The local application is about coordinating your home search with financing certainty. The federal announcement applies nationwide; it supplies no Austin-specific lender requirements or approval data.
Frequently asked questions
Can I use another noncitizen buyer’s document checklist?
Use it only to generate questions. Their circumstances and loan program may differ from yours. Request the requirements that apply to your accurate information from each lender you are considering; another applicant’s experience does not establish your eligibility.
Does this announcement answer whether I can legally own a particular property in Texas?
No. Its subject is federal credit guidance, not a determination of property-ownership rights. If your purchase raises an ownership-law question, seek advice specific to that question from a qualified attorney rather than treating a lender’s eligibility response as the answer.
Sources
- CFPB and DOJ: Withdrawal of Joint Statement on Fair Lending and Credit Opportunities for Noncitizen Borrowers. Page last modified January 12, 2026. Nationwide agency statement; it does not determine individual mortgage eligibility.
Recommended reading
- Mortgage Quote Higher Than the Headlines? Compare the Loan, Not Just the Rate
- Austin Buyer Strategy Guide for Smart Homebuyers
Planning an Austin-area purchase while a lender reviews your eligibility? Contact Vladimir Baibus · ATXCasa, with LPT Realty, for help coordinating your home search and proposed offer timing around the financing questions your lender still needs to resolve.